Every business that extends credit faces the possibility that a customer or borrower won’t pay on time, or at all. Credit Risk Management Solutions give companies a structured way to identify, measure, and control that risk before it damages profitability. Whether you are a bank, a lender, a fintech startup, or a business offering trade credit, the right approach to credit risk keeps your cash flow steady and your growth sustainable.
What Is Credit Risk Management?
Credit risk management is the process of evaluating the likelihood that a borrower will fail to meet their financial obligations, then putting controls in place to limit the resulting losses. It covers everything from screening new applicants to monitoring existing accounts and recovering overdue payments. A strong program protects capital, supports regulatory compliance, and helps leaders make confident lending decisions.
Why Credit Risk Management Matters
Unmanaged credit exposure can quickly turn into bad debt, strained liquidity, and lost investor confidence. Economic downturns, rising interest rates, and industry shocks make repayment less predictable, so businesses that rely on guesswork are the first to suffer. Proactive credit risk management helps you:
- Reduce the rate of defaults and write-offs
- Improve cash flow forecasting
- Price loans and credit terms more accurately
- Meet regulatory requirements such as Basel III and IFRS 9
- Build stronger, longer-lasting customer relationships
Key Components of an Effective Credit Risk Strategy
1. Credit Assessment and Scoring
The foundation of any strategy is a clear picture of the borrower’s creditworthiness. This involves reviewing credit reports, financial statements, payment history, and debt-to-income or debt-service ratios. Scoring models turn these data points into a consistent, objective rating, so decisions don’t depend on gut feeling.
2. Risk-Based Pricing and Credit Limits
Not every customer carries the same level of risk, and your terms should reflect that. Higher-risk borrowers may receive lower limits, shorter payment terms, or higher interest rates, while reliable customers earn better terms. This keeps you competitive without overexposing the business.
3. Continuous Monitoring
A borrower who looked safe six months ago may be struggling today. Ongoing monitoring of payment behavior, credit bureau updates, and market conditions lets you spot early warning signs and act before an account becomes delinquent.
4. Portfolio Diversification
Concentrating credit among a few customers or one industry increases vulnerability. Spreading exposure across sectors, regions, and customer sizes reduces the impact of any single default.
5. Collections and Recovery Planning
Even with strong controls, some accounts will become overdue. A defined collections process, with automated reminders, escalation steps, and clear communication, improves recovery rates and shortens the time it takes to get paid.
The Role of Technology and Automation
Manual spreadsheets and disconnected systems make it hard to see risk in real time. Modern platforms use data analytics, machine learning, and automated workflows to evaluate applicants in seconds, flag unusual patterns, and run stress tests across an entire portfolio. Automation also reduces human error and frees your team to focus on strategic decisions rather than repetitive data entry.
Common Credit Risk Challenges and How to Overcome Them
Many organizations struggle with poor data quality, inconsistent approval criteria, and limited visibility across departments. The fix starts with centralizing customer data, standardizing credit policies, and reviewing them regularly. Training staff to interpret risk signals and aligning sales, finance, and risk teams around shared goals also makes a measurable difference.
Conclusion
Choosing the right Credit Risk Management Tools allows you to automate credit scoring, monitor customer behavior, and respond quickly to emerging risks. When these tools are paired with clear policies and a well-trained team, they become a competitive advantage rather than just a safeguard. Businesses that invest in them early are better prepared for uncertainty and better positioned to grow with confidence.
In short, managing credit risk is not about avoiding risk entirely but about understanding it, pricing it correctly, and staying prepared for the unexpected. Start by assessing your current process, close the gaps, and build a system that evolves with your business.
Frequently Asked Questions (FAQs)
1. What are the main types of credit risk?
The main types are default risk (the borrower fails to repay), concentration risk (too much exposure to one customer or sector), country risk (instability in a borrower’s region), and downgrade risk (a decline in the borrower’s credit rating).
2. How do you measure credit risk?
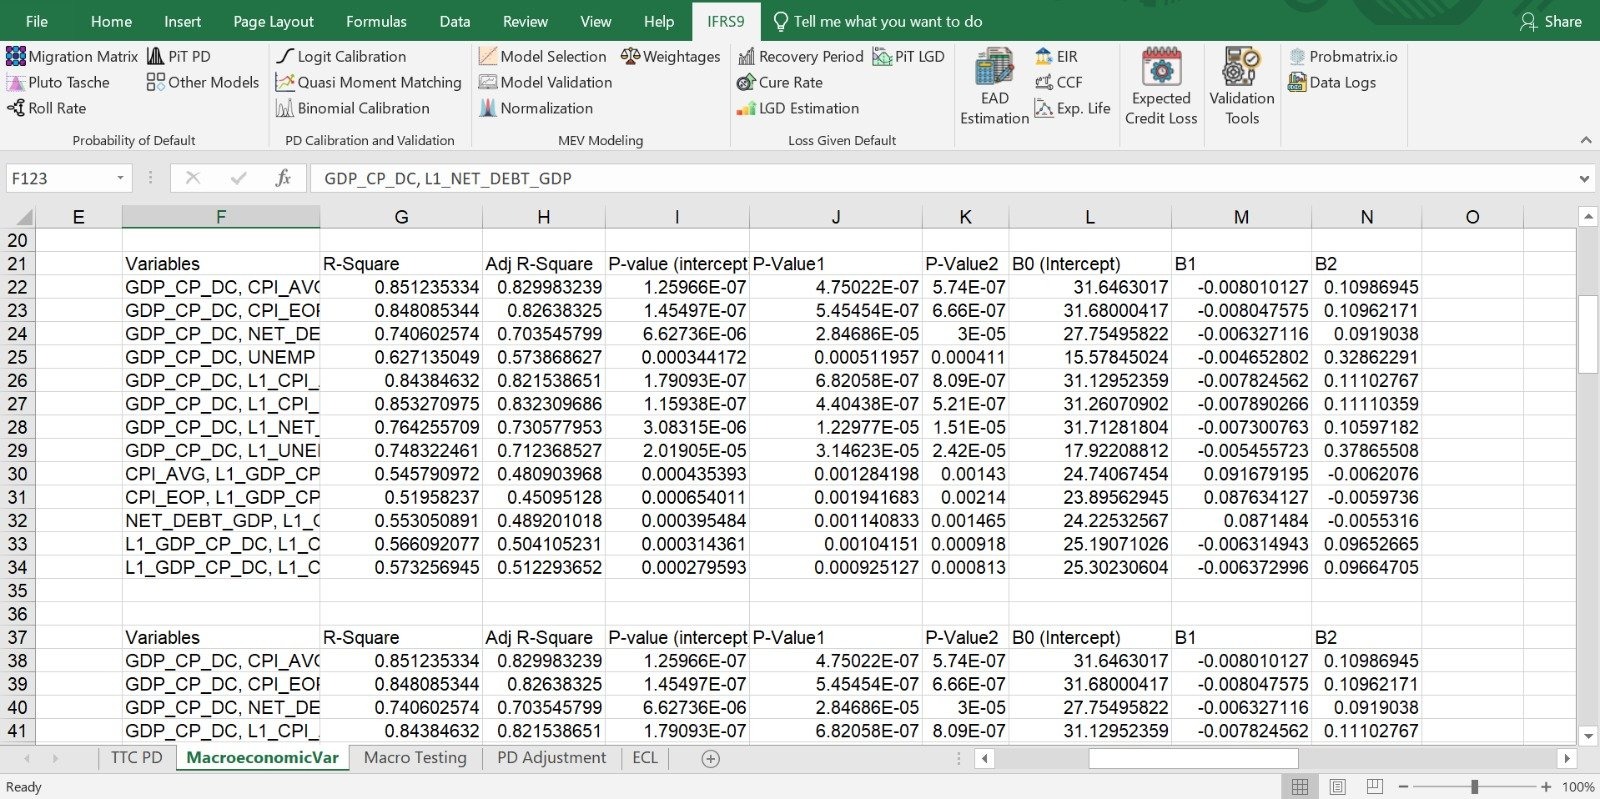
Credit risk is typically measured using credit scores, financial ratio analysis, and metrics such as probability of default (PD), loss given default (LGD), and exposure at default (EAD).
3. Who needs credit risk management?
Banks, lenders, insurers, fintech companies, and any business that sells on credit terms benefit from managing credit risk.
4. How can small businesses reduce credit risk?
Small businesses can run credit checks on new customers, set clear payment terms, require deposits where appropriate, monitor overdue accounts, and use automated invoicing and reminders.
5. How often should credit risk be reviewed?
At minimum, review credit policies and key accounts quarterly. High-risk accounts and volatile market conditions call for more frequent monitoring.
6. Can automation really improve credit risk management?
Yes. Automation speeds up decisions, improves accuracy, enables real-time monitoring, and reduces human error, which leads to fewer defaults and faster payments.