With the increasing demand for quick financial solutions, mobile loans have emerged as a popular option for many individuals looking to borrow money. In today’s fast-paced world, people often seek financial assistance through mobile loan apps, which promise convenience and accessibility. However, understanding mobile loans is vital to making informed decisions. This article provides practical pointers to help you navigate the world of mobile loans effectively, with a focus on utilizing a 15000 loan app.
What is a Mobile Loan?
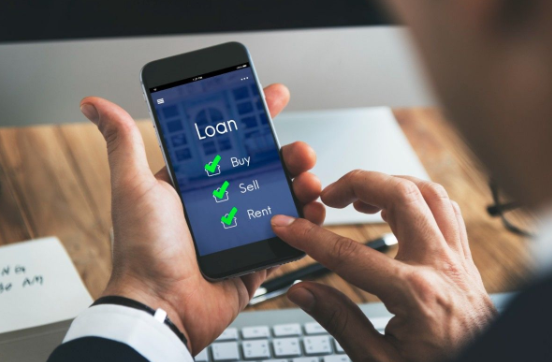
A mobile loan refers to any form of borrowing that is facilitated through a mobile application. These loans are often smaller in amounts, requiring less documentation and a quicker approval process compared to traditional loans obtained through banks or credit unions. They cater primarily to consumers who need immediate funds for emergencies, unexpected expenses, or short-term needs.
Benefits of Taking Out a Mobile Loan
- Convenience: Users can apply for loans anytime and anywhere using their smartphones. This convenience makes the application process seamless and quick.
- Fast Approval: Mobile loan apps typically offer fast approval times, often within minutes, allowing users to receive money quickly if required.
- Minimal Documentation: Unlike traditional loans that require extensive paperwork, mobile loans usually require minimal documentation, often limited to personal identification and income verification.
- Accessibility: Mobile loans are easily accessible to individuals with less-than-perfect credit histories, making them an excellent option for people who may struggle to secure traditional loans.
Understanding the Types of Mobile Loans
Mobile loan come in various forms, each catering to different needs. Understanding these types will help users select the right loan for their situation.
1. Personal Loans
Personal loans are unsecured loans that can be used for any personal expenses, such as medical bills, home repairs, or debt consolidation. Personal loans from mobile loan apps typically range from a few hundred to tens of thousands of dollars with flexible repayment terms.
2. Cash Advance Loans
Cash advance loans are short-term loans that provide quick cash instantly. These are ideal for individuals who need immediate funds but can be expensive due to higher interest rates.
3. Payday Loans
Payday loans are small, short-term loans intended to bridge the gap until the borrower receives their next paycheck. Although these loans are easy to obtain, they can come with exorbitant fees and interest rates.
Using a 15000 Loan App
If you’re considering a mobile loan, a 15000 loan app can provide you with access to a personal loan of up to $15,000. These apps typically offer competitive interest rates and flexible repayment terms, making them appealing options for borrowers. However, before you proceed, consider the following pointers:
1. Read Customer Reviews and Ratings
Before choosing a loan app, make sure to read user reviews and ratings available online. This will give you insight into the experiences of previous customers, helping you gauge the reliability and service quality of the app.
2. Understand the Fees Involved
Different loan apps have varying fee structures. Some may charge application fees, or prepayment penalties, while others may have hidden charges. Always read the fine print to avoid unpleasant surprises.
3. Check the Interest Rates
Interest rates can significantly impact the total amount repayable. Compare the interest rates of various 15000 loan apps and choose the one that offers the most favorable terms.
4. Know Your Repayment Terms
Understand the repayment terms and conditions before committing to a loan. Check how long you will have to repay the loan, the frequency of repayment, and what happens if you miss a payment.
Evaluating Your Loan Options
When considering a mobile loan, it’s essential to evaluate all your options carefully. Here’s how you can do that:
1. Calculate Total Loan Costs
Use online calculators to compute the total cost of borrowing, including principal, interest, and any fees involved. This will give you a clearer picture of what you’ll end up paying.
2. Assess Your Financial Status
Before taking out a loan, assess your current financial standing. Can you afford the monthly repayments without compromising your essential needs?
3. Explore Alternative Sources of Financing
Consider other financing options, such as credit cards or traditional personal loans, especially if you have good credit. These alternatives may offer better terms compared to mobile loans.
The Application Process: Step by Step
Applying for a mobile loan through a 15000 loan app is typically straightforward. The following steps outline the general process:
- Download the App: Start by downloading the loan app from a reputable source, like the App Store or Google Play.
- Sign Up: Create an account by providing the necessary personal and financial information.
- Select Loan Amount: Choose the amount you wish to borrow, ensuring it aligns with your needs and repayment capacity.
- Submit Documents: Upload the required documentation, such as identification and proof of income.
- Review Terms: Carefully review the loan terms before signing the agreement.
- Receive Funds: Once approved, the funds are typically disbursed to your bank account quickly.
Conclusion
Mobile loans offer a practical solution for individuals in need of quick financial assistance. By utilizing a 15000 loan app, borrowers can access a sum adequate for various needs such as emergencies or unexpected expenses. However, it’s crucial to approach mobile loans with caution. Understanding the loan types, evaluating your options, and being aware of the costs involved can significantly improve your borrowing experience. Armed with these practical pointers, you can navigate the world of mobile loans more confidently, ensuring that you make well-informed decisions that align with your financial goals.